

Share
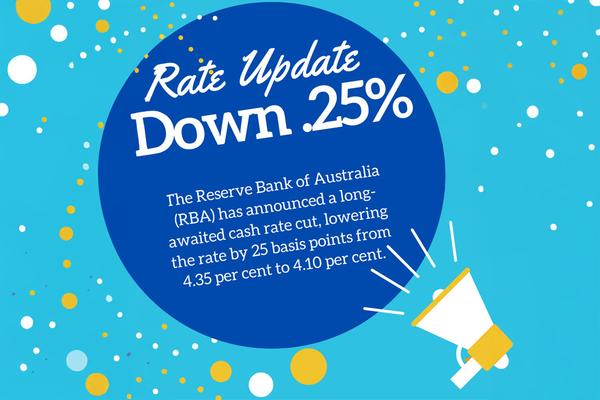
The Reserve Bank of Australia (RBA) has lowered the cash rate by 25 basis points to 4.10 percent.
The RBA rate cut in February 2025 lowered the cash rate by 25 basis points to 4.10 percent, the first reduction since November 2020. For a $750,000 mortgage, that could mean around $120 a month off repayments if your lender passes on the full cut. Market analysts forecast a measured easing cycle, though further cuts depend on incoming data.
This February decision marks the first rate reduction since November 2020. For an Australian homeowner with a $750,000 mortgage, this translates to potential savings of around $120 per month on their repayments, if their lender passes on the full cut.
The timing of this rate cut reflects growing confidence within the RBA that Australia is making substantial progress in its battle against inflation. The reduction comes after months of holding rates steady, with the central bank carefully balancing the need to control inflation against supporting economic growth. The cash rate peaked at 4.35 percent in late 2023, making this cut a significant change in direction.
Why did the RBA cut rates in February 2025?
Recent economic data has presented a compelling case for easing monetary policy. The December quarter showed underlying inflation at 3.2 percent – a marked improvement from previous readings and moving closer to the RBA’s target band of 2-3 percent. This improvement in inflation has occurred alongside modest economic growth and a gradual easing in wage pressures.
The Australian economy currently presents a complex mix of indicators. While inflation is moderating faster than expected, other economic signals remain mixed. Private sector spending has been subdued, with businesses reporting increased difficulty in passing on cost increases to consumers. This suggests that higher interest rates have been effectively cooling demand, one of the key goals of the RBA’s previous tightening cycle. Refinancing traps to avoid after a rate cut.
Despite expectations of softening, recent data indicates the job market remains remarkably resilient. Business surveys consistently show that labour availability continues to constrain many employers, while measures of underutilisation have declined. This tightness in the labour market remains a key consideration for the RBA, as it could potentially impact inflation. Questions to ask before refinancing your home loan.
International context
Australia’s rate cut aligns with a broader global trend, as central banks worldwide begin to ease monetary policy in response to moderating inflation. However, the pace of easing varies significantly across countries. Recent developments, particularly in the United States, suggest a more measured approach to rate reductions than markets had initially anticipated. This global context influences Australia’s monetary policy decisions, particularly given its impact on exchange rates and international trade.
Will there be more RBA rate cuts?
Possibly, but the RBA has been careful to manage expectations about future rate movements. While this cut represents a significant shift, the central bank emphasises that monetary policy remains restrictive and will continue to be so. This suggests that while further cuts may be possible, they are likely to be gradual and data-dependent.
Market analysts are forecasting a measured easing cycle through 2025, with most predicting the cash rate to settle between 3.35 and 3.85 percent by year’s end. However, these projections remain highly dependent on incoming economic data, particularly inflation readings and labour market statistics.
The rate cut is expected to have varying effects across different sectors of the economy:
- Housing Market: The reduction in borrowing costs could provide support to property prices, though affordability constraints remain significant.
- Consumer Spending: Lower mortgage payments may free up household budgets, potentially supporting retail spending.
- Business Investment: Reduced borrowing costs could encourage business expansion, though uncertainty about future economic conditions may temper this effect.
- Financial Markets: The Australian dollar may face some downward pressure, while bond markets adjust to the new rate environment.
While the rate cut represents positive progress in managing inflation, several risks remain. The RBA is particularly concerned about the possibility that easing policy too quickly could stall the disinflation process. Additionally, global uncertainties, including geopolitical tensions and international trade dynamics, continue to pose risks to the economic outlook. What rising prices mean for your home loan strategy.
The RBA’s decision-making process remains firmly anchored to incoming economic data. Key indicators that will influence future decisions include:
- Quarterly inflation readings
- Monthly labour market statistics
- Measures of consumer spending and business confidence
- Global economic developments
- Wage growth indicators
- Productivity measures
The February rate, while providing welcome relief to home loan borrowers, also signals the RBA’s growing confidence in the inflation outlook. However, the central bank’s cautious approach suggests a careful balancing act will continue, ensuring that inflation returns sustainably to target while supporting economic growth. What lower interest rates mean for property prices.
As 2025 unfolds, the effectiveness of this policy shift will become clearer. For now, the RBA appears set to maintain its data-dependent approach, ready to adjust policy as needed while keeping a watchful eye on both domestic and international developments. This balanced strategy aims to guide the Australian economy toward stable growth with controlled inflation.
If you’d like to check whether your lender has passed on the cut, Attain Loans is a Melbourne’s western suburbs mortgage broker that can review your home loan with you.
This article is general information only and doesn’t take into account your objectives, financial situation or needs. Consider whether it’s appropriate for you and speak with a licensed professional before making a decision.
Further questions
What does the RBA rate cut mean for mortgage holders?
Will there be more rate cuts in 2025?
How will this rate cut affect the housing market?
What does this mean for the Australian economy?
How does Australia's rate cut compare to other countries?
This is general information only and is subject to change at any given time. Your complete financial situation will need to be assessed before acceptance of any proposal or product.