

Share
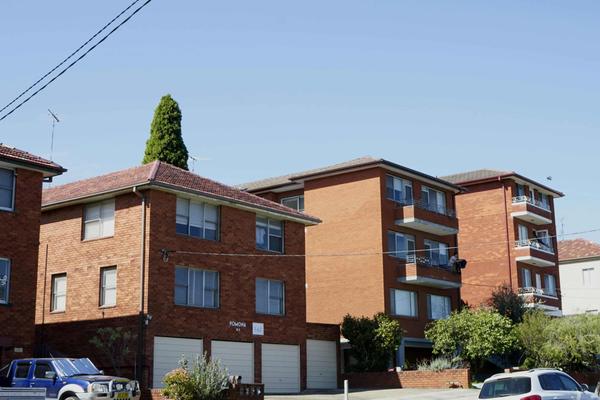
Property investors in Australia seek smart pathways into real estate. Many start by renting where they live while buying investment properties in growth areas. This method, called rentvesting, helps build wealth through rental income and capital gains. Tax advantages and lower entry costs add extra appeal for new investors wanting to expand their portfolios.
Rentvesting means renting where you want to live while buying an investment property in a more affordable area. The rental income helps offset mortgage costs, the strategy separates the emotional side of home ownership from the financial benefits, and the property can build equity through capital growth. Holding cash reserves for repairs and vacant periods helps manage the risks.
Property ownership paths in Australia often start with buying a home. Yet buying an investment property through rentvesting can work as a better way to build wealth.
What is rentvesting and how does it work?
Rentvesting lets investors buy property in affordable areas while renting where they want to live. With property prices continuing to rise in major capital cities, many Australians need new ways to enter the market. This approach splits the emotional aspects of home ownership from the financial benefits of property investment.
The rental income helps offset mortgage costs, making the property easier to maintain long-term. Property investors may be able to claim tax deductions that aren’t available to owner-occupiers, such as repairs, maintenance, insurance and loan interest. Speak with your accountant or tax adviser about your circumstances.
Good debt vs bad debt in property
Investment properties create good debt by generating income through rent and tax benefits. The debt works to build wealth rather than drain resources. Owner-occupied homes represent bad debt as they cost money without producing income. This key difference means investment properties can strengthen financial positions and may boost borrowing capacity, although investment debt still carries risk if rents fall or the property sits vacant.
Many banks view investment property loans more favourably than owner-occupier mortgages. The rental income and tax advantages can improve serviceability calculations. This can make it easier to qualify for additional loans and expand a property portfolio over time, subject to lender assessment.
Is rentvesting a good idea for first-time investors?
Starting with an investment property allows buyers to enter the market at lower price points than many owner-occupied homes require. This can help investors build equity faster through both capital growth and rental returns. The investment can then act as a stepping stone toward buying a home to live in later. Important factors when selecting your investment property.
Investment properties tend to perform better financially when buyers focus purely on growth metrics rather than emotional factors. Key indicators include local infrastructure development, population growth, rental demand and affordability relative to surrounding areas.
Building long-term wealth through property
Property investors should take a long-term view, aiming to hold assets through multiple market cycles. Over time, well-chosen properties tend to increase in value beyond their purchase price and ongoing costs. The combination of capital growth, rental income and tax benefits helps create wealth steadily.
Regular rent reviews help maximise returns, while preventative maintenance protects the property’s value. Investors should maintain cash reserves for repairs and vacant periods. This reduces stress and prevents forced sales during market downturns. SMSF property investment.
What are the tax benefits of rentvesting?
The Australian tax system may offer a range of potential benefits to property investors. These include deductions for property management fees, council rates, insurance premiums and maintenance costs. Investors may also be able to claim depreciation on buildings and fixtures, potentially reducing taxable income without affecting cash flow.
Negative gearing may allow investors to deduct property losses against other income when costs exceed rental returns. This potential tax benefit can make it easier to hold properties during growth phases when rental yields might be lower, but it still means the property is running at a loss. Speak with your accountant or tax adviser about your circumstances.
Choosing investment locations
Research remains critical when selecting investment areas. Look for locations with diverse employment options, good transport links and plans for infrastructure improvements. Areas with multiple growth drivers tend to perform better than those relying on single industries.
Consider factors like rental vacancy rates, tenant demographics and local development applications. These indicators help predict future property performance. Areas going through gentrification often offer good growth potential as their amenity levels improve.
If you’re weighing up rentvesting, a mortgage broker in Melbourne West can help you compare investment loan options and understand your borrowing capacity before you buy. This article is general information only and doesn’t take into account your objectives, financial situation or needs. Consider whether it’s appropriate for you and speak with a licensed professional before making a decision.
Further questions
What deposit do I need for an investment property in Australia?
Can I use my superannuation to buy an investment property?
What insurance do property investors need?
How does the ATO view short-term rental investments?
What impact does zoning have on investment properties?
This is general information only and is subject to change at any given time. Your complete financial situation will need to be assessed before acceptance of any proposal or product.